Are You Confident You Have the Right Insurance Cover?
Amber Wealth can help you review Life, TPD, Trauma and Income Protection—whether held through super or in personal policies. We consider your existing cover alongside your family, income, commitments and broader financial plan. A review starts with understanding what you have, not an assumption that you need to replace it.
45 minutes · Complimentary · No obligation to change anything
- Corporate Authorised Representative of Lifespan Financial Planning Pty Ltd, AFSL 229892
- Brighton office, or by video
- More than 15 years in financial services
- Personal experience supporting clients through claims
What does each type of cover actually do?
Pays: A lump sum under the policy's ownership and beneficiary arrangements
Trigger: An accepted death claim, or a qualifying terminal illness where included
The catch: For cover inside super, the benefit is paid to the trustee first. Nominations, super rules and the recipient's tax status affect who receives the money and its tax treatment.
General information only. Definitions, exclusions and benefit limits vary between insurers and products. Check your current PDS, policy schedule and any personal exclusions; claims are subject to assessment.
Being covered and being covered for enough aren't the same thing
Your cover
Life, TPD, Trauma and Income Protection each address different events
Your circumstances
Debts, dependants, income and available savings shape the review
Your decision
Review existing terms before deciding whether anything should change
General information only. Policy terms, eligibility and claim requirements vary; a review does not assume your existing cover needs replacing.
Does any of this sound familiar?
- You've had two or three jobs, and each one opened a new super account — so you might be paying for TPD or life cover three times over without realising it.
- You've never actually seen what your default cover through super would pay, or what has to happen before it does.
- You assumed trauma cover came bundled with your super. It doesn't, and hasn't for anyone who joined after mid-2014.
- You're the main income earner in your household and you don't have income protection at all.
- Your cover was set up years ago — before the mortgage, before the kids, before your income looked like it does now.
None of these mean your cover is wrong. They mean it's worth twenty minutes to find out.
The Insurance Review
Forty-five minutes with Adam Sobczak, in the Brighton office or by video. Bring whatever you've got — a super statement, an old policy document, or just your best guess. You'll leave with a plain-English picture of where you stand, whether or not you go any further with us.
What you're actually covered for
A plain-English read of your current policies, inside and outside super — what triggers a payout, what doesn't, and what definition applies if you ever need to claim.
Where the gaps and overlaps are
Check possible overlaps across super accounts, the definitions and exclusions that apply, and whether insured amounts reflect your current commitments.
What's worth changing, and what isn't
A clear view of what to keep as-is, what to restructure, and what — if anything — is genuinely worth replacing, with the trade-offs and any cost spelled out in writing before you decide anything.
There's no cost and no obligation, and no assumption you'll replace anything. If your current cover is well structured, we'll tell you that too.
New to cover entirely? Get a life insurance quote · For business insurance needs, see our personal insurance services.
How it works
01
Tell us what you think you have
A short form. Your name, how to reach you, and a rough idea of what cover you hold and where. Takes under a minute — "not sure" is a completely fine answer.
02
We talk for 45 minutes
Brighton office or video. If you can find a recent super statement or a policy document, bring it — if not, we'll work from what you know and chase the rest.
03
Agree the next steps
We explain the information needed for a review and agree the scope, fees and next steps if you want personal advice. Any recommendation depends on understanding your circumstances and current policy terms.

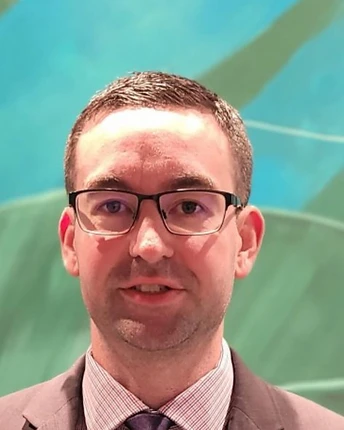
You'll be talking to Adam — including if you ever need to claim
Adam Sobczak is Director & Senior Financial Planner at Amber Wealth. He has worked in Australian financial services since 2010, including roles at CBA, NAB, ANZ and the industry fund TelstraSuper, as well as boutique practices around the country.
He holds the Diploma and Advanced Diploma of Financial Planning and is accredited to advise on SMSF and margin lending. He graduated from Victoria University in 2012, majoring in Financial Risk Management and International Trade.
Insurance advice doesn't stop at the policy. Adam supports clients directly if a claim ever needs to be made — not handed off to a call centre.
Insurance is considered alongside your wider circumstances, not as an isolated product. Learn more about Adam and Amber Wealth, explore our financial planning approach, or use the insurance guide to understand each type of cover.
- Dip. FP
- Adv. Dip. FP
- SMSF accredited
- Brighton, VIC
Questions people ask before they book
What can I include in an insurance review?
We can review Life, TPD, Trauma and Income Protection, including cover through super and personal policies. Choose one type, multiple types or Not sure in the enquiry form. We consider your current cover in the context of your broader financial circumstances.
What's the difference between TPD and trauma insurance?
TPD applies the policy's permanent disability definition. Trauma applies the medical criteria for a specified event or condition, and does not generally require permanent inability to work. Neither is automatically payable on a diagnosis; exclusions and other claim conditions apply.
Can I get trauma insurance through my superannuation?
Super funds do not offer new trauma cover. Some arrangements established before July 2014 may remain, so check your statement. New trauma insurance is generally held outside super, either separately or linked to another policy.
Is the TPD cover in my super own occupation or any occupation?
Check the specific wording. Super cover commonly uses an any occupation test, but functional definitions or other work-status conditions may apply. Insurer approval and the trustee's condition-of-release assessment are separate. Do not assume the policy name explains the full test.
How much of my income does income protection replace?
There is no single percentage that applies to every policy or claim. The amount depends on insurable earnings, the selected cover, policy limits and offsets for other payments. Benefits may change during a claim and are generally taxable.
Do I need income protection if I already have TPD cover?
They address different risks. Income protection can pay during an eligible temporary or ongoing disability, up to its benefit period. TPD generally pays a lump sum for an eligible permanent disability. Whether you need either or both depends on your resources, commitments and policy terms.
What information do I need for the first enquiry?
Your name, email, phone, preferred contact method and the cover you would like to discuss are enough to start. Do not send medical records, account numbers or other sensitive information through this initial form. We can explain what documents are needed later.
Will an insurance review mean cancelling what I already have?
Not necessarily. A review may identify reasons to retain existing cover. Any proposed replacement needs careful comparison, including costs, underwriting, exclusions and features that could be lost. Do not cancel existing cover before understanding and confirming any replacement.
What does an Insurance Review cost?
The initial Insurance Review is complimentary. If you decide to proceed with personal advice, the scope, fees and relevant remuneration will be explained before you commit. There is no obligation to proceed after the initial discussion.
Who is Amber Wealth licensed by?
Amber Wealth is a Corporate Authorised Representative of Lifespan Financial Planning Pty Ltd, AFSL 229892. You can request our Financial Services Guide and adviser profile to understand our authorisations and how advice is provided.
Book an Insurance Review
Tell us how to reach you and what you would like to review. Any follow-up details are optional.
Find out what you're actually covered for.
Start with a complimentary conversation about your existing cover and the questions you want answered. There is no assumption that you need to change a policy.
Or call 03 9964 0718 — you'll get Adam or someone who works with him.