Have I got enough to retire?
It's the question most people in their fifties turn over at 3am and never get a straight answer to. In 45 minutes we'll give you one — a real number, based on your super, your savings, and the life you actually want to live.
45 minutes · Complimentary · No obligation to proceed
- Corporate Authorised Representative of Lifespan Financial Planning Pty Ltd, AFSL 229892
- Brighton office, or by video
- More than 15 years in financial services
- Retirement, super and Age Pension specialists
What does the retirement you want actually cost?
That lifestyle costs about
$78,566
The full Age Pension provides $47,070. That leaves $31,496 a year you need to fund yourself.
ASFA estimates you'd need around $730,000 in super at 67 to cover it.
Source: ASFA Retirement Standard, March quarter 2026, for homeowners aged 65–84. Age Pension figures include supplements. Lump sums assume retirement at 67, drawdown of capital and receipt of a part Age Pension. These are general benchmarks, not a projection of your own position.
Most people are out by more than they think
$78,566
What a comfortable retirement costs an Australian couple each year
$47,070
What the full Age Pension pays a couple, including supplements
$31,496
The annual gap your super and savings have to cover
Those are national averages. Your number depends on your mortgage, your health, when you stop work, and how long you live. That's the number worth knowing.
Does any of this sound familiar?
- You've got super sitting in two or three funds and you couldn't say exactly what's in them.
- Someone has told you "you'll be fine" — but nobody has ever shown you the maths.
- You'd like to stop at 60, not 67, and you don't know whether that's realistic or wishful.
- You worry about running out at 85. You also worry about dying with a pile you never spent.
- Your last review was with an adviser who has since left the firm.
None of these are unusual. All of them are solvable once you can see the numbers.
The Retirement Readiness Review
Forty-five minutes with Adam Sobczak, in the Brighton office or by video. You'll leave with three things written down — whether or not you go any further with us.
Your retirement number
What the life you're picturing actually costs each year, in today's dollars — not a national average, your figure.
Where you're on track to land
What your super, savings and likely Age Pension entitlement are projected to deliver, and what that means for the retirement date you have in mind.
The three levers that matter most
Of everything you could change — contributions, structure, investment mix, timing, or when you stop — which ones actually move your outcome, and by how much.
There is no cost and no obligation. If we're not the right fit, we'll tell you, and you keep the numbers either way.
How it works
01
Tell us where you're at
A short form. Your name, how to reach you, and roughly where things sit. Takes under a minute.
02
We talk for 45 minutes
Brighton office or video, whichever suits. Bring a recent super statement if you have one handy — if not, we'll work with what you know.
03
You get your numbers
A written summary within five business days. Yours to keep. No follow-up sales sequence, no pressure.

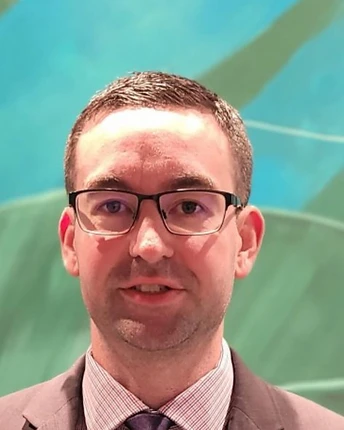
You'll be talking to Adam — not a call centre
Adam Sobczak is Director and Principal Adviser at Amber Wealth. He has worked in Australian financial services since 2010, including roles at CBA, NAB, ANZ and the industry fund TelstraSuper, as well as boutique practices around the country.
He holds the Diploma and Advanced Diploma of Financial Planning and is accredited to advise on SMSF and margin lending. He graduated from Victoria University in 2012, majoring in Financial Risk Management and International Trade.
Amber Wealth is a boutique practice in Brighton. Adam sees every client personally.
- Dip. FP
- Adv. Dip. FP
- SMSF accredited
- Brighton, VIC
Questions people ask before they book
Book your Retirement Readiness Review
Two steps. The first takes about thirty seconds.
Stop guessing. Get the number.
Forty-five minutes, no cost, no obligation. You'll leave knowing where you actually stand.
Or call 03 9964 0718 — you'll get Adam or someone who works with him.